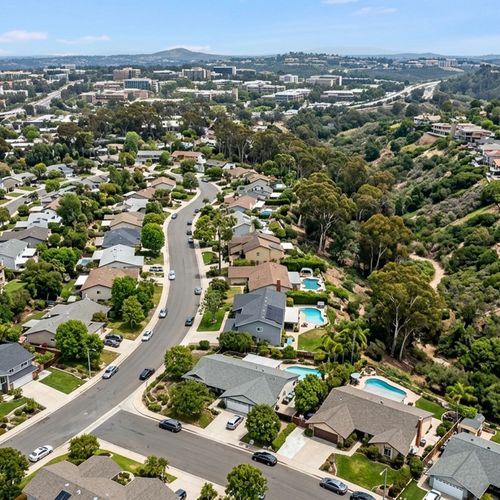


Assisted living in the University City area starts around $5,282 per month, with broader San Diego averages running between $4,500 and $6,000. Those numbers add up fast, and covering them month after month takes real planning - especially for older adults moving onto fixed incomes who are considering senior downsizing in University City, San Diego.
For a lot of local homeowners, the answer is already sitting in their driveway. Selling a house in University City, San Diego, lets retirees convert what is essentially a locked-up asset into the cash they need to move into a senior living community on their own terms.
Why Selling a Home Makes Sense for Senior Living Funding
The median sale price in University City sits around $858,700 as of mid-2026. That's a substantial number, and for homeowners who've been here a while, it represents a direct path to covering a continuing care retirement community or assisted living facility.
There's also something to be said for removing the financial noise that comes with owning a house. No more surprise roof repairs. No more rising utility bills. Just a predictable monthly care fee and the peace of mind that comes with it.
Accessing Home Equity to Pay for Care
Most homeowners in the 92122 ZIP code have been building equity for a decade or more. Cashing that out gives you a lump sum that can handle community entrance fees - costs that often require significant capital upfront before anything else gets figured out.
What's left after the entrance fee gets paid can go into interest-bearing accounts or investments. The yields from those accounts can then help carry the ongoing monthly costs without drawing down the principal too quickly.
Dropping Maintenance and Property Tax Expenses
Property taxes, landscaping, routine upkeep - these bills don't stop just because someone is spending most of their time elsewhere. They quietly drain resources that would be better directed toward care or medical expenses.
The day a sale closes, those outflows stop. It's one of the cleaner financial benefits of selling that doesn't always get enough attention.
California Tax Rules for Home Sellers
California follows federal IRS rules on primary residence sales. Single filers can exclude up to $250,000 in profit from capital gains taxes; married couples filing jointly can exclude up to $500,000. Gain above those thresholds gets taxed as ordinary income at the state level, and California's rates climb as high as 13.3%.
Running these numbers before you list - not after - gives you a clearer picture of what you'll actually walk away with.
Capital Gains Exclusions on Primary Residences
To qualify for the exclusion, you need to have owned and lived in the home as your primary residence for at least two of the five years immediately before the sale. That rule works in favor of longtime University City homeowners who are finally ready to make the move.
One thing worth doing before you close: sit down with a tax professional and nail down your cost basis. If you've put money into renovations over the years, adding those costs to your original purchase price can reduce the total taxable gain.
How Proposition 19 Impacts Property Taxes
Not everyone is ready to sell outright. If you're considering moving to a smaller home or a lower-tier care community rather than fully liquidating, California's Proposition 19 is worth understanding. Homeowners aged 55 and older can transfer their current property's low taxable base value to a replacement primary residence anywhere in the state.
That transfer can be used up to three times in a lifetime, and it applies even if the new home costs more. For anyone on a fixed income, avoiding a property tax reassessment can make a meaningful difference in the monthly budget.
Local Real Estate Market Conditions in University City
Right now, homes in University City are going under contract in roughly 23 days, and with only about 2.8 months of supply on the market, sellers are in a reasonable position. Recent data shows homes selling for about 98% of list price on average - which means accurate pricing matters, but you're not facing a market that forces deep discounts.
Current Property Values and Sale Timelines
Early 2026 estimates from Zillow and Redfin ran slightly higher, but current MLS data puts the median sale price at around $858,701. Pricing to recent comparable sales keeps a listing from sitting too long, which is the last thing you want when a move-in date at a care community is already on the calendar.
That 23-day average also gives families something to work with when coordinating timing. Moving out before listing tends to make the home easier to show, which generally smooths out the closing process.
Deciding Between As-Is Sales and Major Repairs
Nearly 22% of homes in the area have recently sold above asking price. That's meaningful context if you're looking at a 1970s or 1980s house and wondering whether you need to gut it before listing.
You probably don't. Buyers in University City often want to handle updates themselves, and sellers who go the as-is route avoid both the out-of-pocket contractor costs and the delays that come with renovation work.
Other Ways to Finance the Transition
Selling outright is the most straightforward path, but it's not the only one. Some families want to hold onto the property, and there are alternatives worth knowing about. Each one comes with its own trade-offs - more management responsibility, more risk, or both.
Leasing Out Your Property
Renting the house generates monthly income that can offset assisted living costs while keeping the property in the family. The equity stays intact, and the home keeps appreciating.
That said, becoming a landlord introduces real complications - property management fees, repair bills, vacancy gaps. The rental income has to be consistent enough to keep up with a senior living facility's payment schedule, and those communities don't offer much flexibility when the rent check is late.
Bridge Loans and Reverse Mortgages
A bridge loan covers a community's entrance fee while the house is still being prepared for sale. Once the property closes, the proceeds pay off the loan. It's a practical tool when timing between move-in and closing doesn't line up neatly.
Reverse mortgages work differently - they let homeowners borrow against equity without selling, but the borrower has to remain in the home as their primary residence. If the owner moves into a long-term care facility for more than 12 consecutive months, the reverse mortgage typically becomes due. That's a detail that catches people off guard, so it's worth knowing upfront.
Frequently Asked Questions
How much of the profit from selling my University City home is exempt from capital gains taxes when moving into a senior care facility?
Single filers can exclude up to $250,000 of profit, and married couples filing jointly can exclude up to $500,000. Any profit above those amounts is taxed at ordinary state income tax rates, which can reach up to 13.3% in California.
Do I need to renovate my older University City home before selling, or will San Diego buyers purchase it as-is?
You don't need to renovate. With University City homes spending roughly 23 days on the market and about 22% selling above list price, many buyers are willing to purchase properties as-is and handle updates themselves.
How can I cover the upfront deposit for a San Diego senior living community before the sale of my University City house officially closes?
Many families use a bridge loan to secure short-term funds for the deposit. That loan gets paid off completely using the proceeds once the home sale finalizes.
Does it make more financial sense to rent my University City house to UCSD students or sell it completely to fund assisted living?
It depends on your tolerance for risk and management. Renting provides ongoing monthly income, but selling outright delivers a large, immediate lump sum without the landlord responsibilities and maintenance costs that come with keeping the property.
How quickly can I expect to liquidate my property in the current University City market if I need immediate funds for a senior care transition?
Properties in the area are currently selling in an average of 23 days. Factor in the standard 30-day escrow period, and a complete liquidation typically takes about two months from list to close.
Will the lump sum from selling my San Diego home disqualify me from Medi-Cal assistance for long-term care?
Yes, it can. Selling your primary residence converts an exempt asset into countable cash, which may push you over California's current $130,000 individual asset limit for Medi-Cal programs.
Check out this article next